Where Did the Seed Round Go
At eight-fifteen on a drizzle-soaked Monday morning in Amsterdam’s Zuidas financial district, I stepped out of the tram holding a judicial receivership warrant issued by the District Court of Amsterdam and a five-kilogram steel toolbox belonging to a bonded master locksmith named Hendrik.
Our destination was the fourteenth floor of an all-glass office tower overlooking the ring canal. The bronze plaque in the lobby declared the tenant to be an "autonomous agentic frontier intelligence platform" that had closed a forty-million-euro Series A funding round sixteen months earlier. The tech press had hailed the twenty-six-year-old founders as visionary pioneers of the post-human economy; the venture capital partners had published breathless threads on social media celebrating their seventy-times forward revenue multiple; and the municipal government had awarded them an innovation tax subsidy.
When Hendrik inserted his hardened pick into the electronic euro-profile cylinder of the main double doors, the mechanism clicked open with a dull, hollow echo.
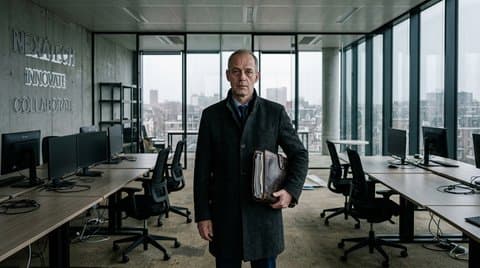
Inside, the corporate morgue was entirely silent. The sixty-thousand-euro Italian espresso machine on the marble island had its steam wand caked in dried oat milk. On the white oak desks sat rows of curved 4K monitors, ergonomic mesh chairs that had never known human lumbar fatigue, and unopened boxes of branded corporate fleece vests. The founders were not present. Their corporate mobile numbers had been disconnected on Friday afternoon; their LinkedIn profiles had been quietly scrubbed; and their passports showed an outbound departure from Schiphol Airport to Dubai thirty-six hours before the judicial decree was signed.
My legal duty as insolvency trustee was dispassionately simple: seal the physical premises, seize the bank accounts, audit the books, and find out where forty million euros in investor capital and three million euros in unpaid trade debt had evaporated in four hundred days.
The Circular Anatomy of Synthetic Revenue
When laymen think of corporate bankruptcy, they imagine a factory that failed to sell enough shoes, or a restaurant that suffered from rising food costs and empty tables. Technology insolvency in the age of generative models belongs to an entirely different taxonomic category: it is a confidence game built upon circular accounting illusions.
When I opened the company’s primary accounts at an institutional Dutch bank, the combined liquid cash balance was seven thousand four hundred and twelve euros.
Where had the forty million euros gone? To uncover the corpse, one must follow the vendor ledger.
Expense Category | Claimed Series A Allocation | Forensic Liquidation Audit Reality |
|---|---|---|
Compute Infrastructure | "Proprietary frontier model training" | 68% paid directly to hyperscale cloud providers |
Sales & Business Development | "Enterprise customer acquisition" | Paid pilot subsidies and circular vendor rebates |
Executive Compensation | "Modest founder living stipends" | Offshore management service fees in Delaware and Cyprus |
Office & Workplace Amenities | "Frictionless engineering environment" | Designer Scandinavian furniture and uncapped culinary catering |
Recoverable Physical Assets | "Over €15M in capitalized assets" | Depreciated server blades worth scrap metal prices at auction |
Over twenty-seven million euros had been wired directly back to two American cloud hyperscalers—the very same corporate entities whose investment arms had contributed five million euros to the original funding round. It was an immaculate financial carousel: the hyperscaler invests balance-sheet cash into the startup at a astronomical paper valuation, and the startup immediately wires eighty percent of that cash right back to the hyperscaler to rent graphics processing units that cost the hyperscaler fifteen cents on the dollar to operate.
The startup was never a viable software business. It was a glorified, debt-funded passthrough entity designed to convert venture capital equity into guaranteed cloud computing revenue for Big Tech infrastructure monopolies.
The Mirage of the Enterprise Pilot
When you cross-reference the customer list with the actual cash receipts, the comedy turns tragic. The company had loudly announced twelve "enterprise production contracts" with European banks, retail conglomerates, and logistics operators.
When I subpoenaed the underlying service-level agreements, I discovered that eleven of the twelve contracts contained confidential side-letters. The customer had agreed to "pilot" the autonomous software only because the vendor had agreed to pay for the integration costs, provide fifty thousand euros in monthly AWS token credits, and embed four full-time software consultants on-site free of charge.
The Insolvency Death Spiral: Subsidized Pilot Launch → Circular Revenue Recognition → Escalating Token Invoices → Venture Capital Retraction → Receivership Padlock
The moment the pilot subsidy expired and the vendor presented an invoice reflecting the actual cost of operating the synthetic models, the customer executed their thirty-day unilateral termination clause. The "annual recurring revenue" that had justified a forty-million-euro post-money valuation was not recurring at all; it was an uninsurable capital drain.
And behind the collapsed carousel sat the real victims: the local catering company that provided daily lunches and was owed forty-two thousand euros; the commercial interior contractor in Utrecht who installed acoustic timber dividers on sixty-day credit; the junior frontend engineers who worked eighty hours a week on false promises of stock options while their statutory pension contributions were secretly diverted to pay the monthly cloud bill.
The Auctioneer’s Gavel
On Thursday morning, the commercial auction began.
There is nothing quite as humbling to technological hubris as an insolvency auctioneer in a high-visibility vest selling the physical detritus of a collapsed unicorn. Bidders from second-hand electronics brokers and logistics warehouses wandered through the rows of walnut desks with clipboards, inspecting asset numbers stuck to aluminum monitor stands.
A cluster of twenty-four custom liquid-cooled server blades that had cost eight hundred and fifty thousand euros eighteen months earlier was knocked down to a refurbished hardware trader from Eindhoven for thirty-two thousand euros. The high-performance compute silicon that had promised to automate European civil law was sold at a ninety-six percent discount to run a Minecraft gaming server in a basement.
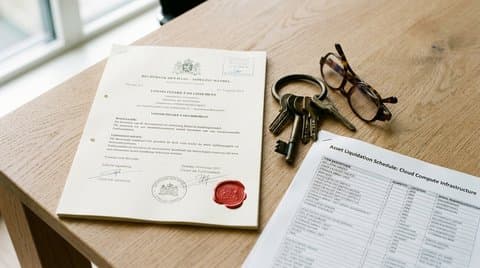 Judicial Bankruptcy Decree and Keys
The ergonomic task chairs went for forty-five euros apiece. The espresso machine went for twelve hundred. The branded fleece vests were discarded in a plastic bin by the service elevator, unfit even for second-hand export.
When the auctioneer’s gavel fell for the final time, the total gross recovery across the entire company stood at one hundred and eighty-six thousand euros—barely enough to cover the court filing fees, the locksmith's invoice, and three weeks of bonded warehouse storage. The trade creditors will receive less than four cents on the euro.
The Illusory Shield of the Delaware Shell
When bankruptcy receivers attempt to pursue clawback litigation against founders who have executed a strategic exit prior to liquidation, we invariably collide with a labyrinth of jurisdictional obfuscation.
In the case of our Zuidas startup, the Dutch operating entity was merely a wholly owned subsidiary of a Delaware holding company, which in turn was managed through a nominee entity registered in Nicosia. Under European corporate law and Article 13 of the European Insolvency Regulation, cross-border asset tracing requires filing reciprocal letters rogatory across multiple jurisdictions—a process that costs hundreds of thousands of euros in judicial fees and takes three to five years to resolve.
The venture capitalists know this. The venture debt lenders know this. By the time a local European court authorizes the unfreezing of offshore accounts, the capital has already been commingled, converted into foreign treasury bills, or rolled into a new investment vehicle operating under a different brand name.
The statutory liquidation preference means that institutional preferred shareholders will fight over the meager auction proceeds, while the unsecured trade creditors—the small catering business, the electrical maintenance contractor, the local cleaning staff—are left holding valueless proof-of-debt certificates.
The Lessons of the Liquidator
As I walked out of the empty tower into the cold rain of Gustav Mahlerplein, the glass facades of neighboring tech offices gleamed against the slate-grey sky. Inside them, dozens of other venture-backed boards were holding emergency strategy sessions, trying to figure out how to explain to their lenders that their gross margins had collapsed and that their autonomous swarms were costing more to run than the human employees they were meant to replace.
The cycle of financial delusion never changes. In the seventeenth century, Amsterdam speculates on tulip bulbs; in the eighteenth, on South Sea trading monopolies; in the twenty-first, on synthetic text pipelines that promise infinite wealth while burning three hundred kilowatts of electricity per paragraph.
The venture capitalists will move on to the next narrative, writing off their investments against general partner carry and raising new funds from gullible sovereign wealth managers. But down here on the ground, in the commercial courts and the liquidation auctions, the laws of double-entry bookkeeping remain as cold and unyielding as Dutch granite.
If an enterprise cannot deliver a service that costs less to produce than what a paying customer will voluntarily hand over without a subsidy, it is not an intelligence revolution. It is an insolvency waiting for a receiver with a key.