The Arithmetic of Enterprise Disillusion
There is an unspoken panic quietly circulating through the mezzanine ballrooms of enterprise software conferences this autumn. It does not appear in the slick keynote decks, nor does it surface in the staged customer testimonials where smiling Fortune 500 executives celebrate their pilot deployments of generative copilots. It appears instead in the private dinner conversations between chief financial officers and audit committee chairs, where the conversation eventually turns to a single, stubbornly uncooperative metric: gross margin erosion.
For three decades, the foundational economic compact of enterprise software was delightfully simple. A company expended capital upfront to engineer a codebase once, encapsulated it into reproducible binaries or multi-tenant cloud instances, and then sold licenses with marginal delivery costs approaching zero. Software gross margins sat comfortably between seventy-five and eighty-eight percent. Wall Street rewarded this immaculate operating leverage by assigning software companies dizzying price-to-revenue multiples of twenty, thirty, or forty times Annual Recurring Revenue (ARR).
Over the past twenty-four months, that economic compact has quietly collapsed under the weight of synthetic compute.
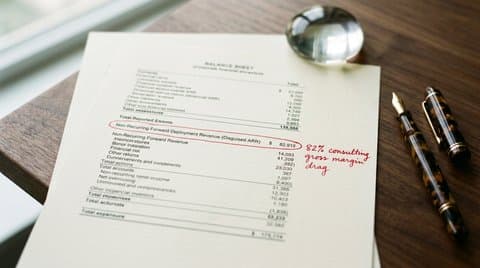
The dirty secret of enterprise artificial intelligence is that what venture capitalists and corporate flacks are reporting as high-margin software recurring revenue is, in forensic reality, glorified custom consulting and subsidized compute arbitrage. When a corporate customer pays two million dollars for an enterprise agentic workflow deployment, eighty percent of that check does not flow down to scalable software gross profits. It evaporates into two immediate black holes: first, the catastrophic inference token bills owed to hyperscale cloud providers; and second, the legions of forward-deployed systems engineers required to manually babysit, prompt-tune, and continuously constrain stochastic models from corrupting enterprise databases.
The Phantom Multiples of Forward Deployment
When you audit the financial disclosures of mid-stage AI enterprise vendors with a forensic lens, the accounting gymnastics become instantly transparent. Under standard GAAP rules, costs directly associated with delivering a contracted service must be categorized under Cost of Goods Sold (COGS). If an enterprise client requires six dedicated machine learning architects embedded on-site for nine months to build custom retrieval harnesses, craft deterministic evaluation gates, and patch semantic drift, those human salaries are not research and development; they are cost of revenue.
Yet, across Silicon Valley and European tech hubs, venture-backed vendors have been systematically burying these massive human operational costs inside capitalized software development or sales engineering line items. By classifying army-scale bespoke consulting as "customer onboarding assistance" or "strategic platform enablement," enterprise vendors artificially inflate their declared software gross margins on paper, convincing secondary markets and crossover funds that they are scaling a software monopoly rather than an overleveraged IT consultancy.
Operational Dimension | Pure Multi-Tenant SaaS (2012–2022) | Generative Enterprise Pipeline (2024–2026) |
|---|---|---|
Gross Margin Profile | 78% – 86% stable baseline | 34% – 52% compressed by dynamic compute |
Marginal Serving Cost | Millicents per database query | Tens of cents per multi-step agent trajectory |
Deployment Cadence | Self-serve or 14-day automated setup | 4 to 9 months of embedded human engineering |
Annual Churn Trajectory | 4% – 7% net negative revenue churn | 28% – 44% gross churn upon pilot renewal |
Valuation Metric | Pure ARR revenue multiples (15x–30x) | Blended professional services multiple (3x–6x) |
The illusion holds only as long as the initial pilot funding lasts. In the corporate software boom of 2023, chief information officers commanded speculative innovation budgets unburdened by rigorous return-on-investment hurdles. Boards of directors demanded an artificial intelligence strategy at any cost. Today, those two-year pilot contracts are coming up for formal enterprise renewal, and procurement officers are performing what can only be described as forensic autopsies on actual corporate productivity.
The findings are uniformly brutal. When enterprise buyers divide the total capital expended—software subscription fees, token overages, internal infrastructure integration, and thousands of hours of internal staff supervision—by the measurable hours saved across the workforce, the implied hourly cost of autonomous agent assistance exceeds the billable rate of a senior partner at a white-shoe law firm.
When the Model Swallows the Unit Economics
Consider the anatomy of a real-world enterprise procurement failure. A global logistics insurer with four thousand underwriters deployed an agentic policy extraction system designed to ingest, summarize, and cross-examine multi-hundred-page commercial maritime bills of lading. The promotional pilot promised ninety percent labor automation and instant fivefold processing throughput.
What the marketing case study omitted was the brutal reality of semantic error propagation. Because a single hallucinated exclusion clause or misattributed deadweight tonnage could expose the underwriting balance sheet to tens of millions of dollars in unhedged maritime risk, the insurer could not permit the autonomous pipeline to commit decisions directly to production databases. Every single synthetic inference required human verification.
The Enterprise Value Destruction Loop: Stochastic Generation → Hallucination Exposure → Mandatory Multi-Pass Redundancy → Human Review Bottleneck → Negative Unit Margin
Instead of liberating underwriters from routine reading, the system transformed them into weary, cynical editors of machine-generated drafts. The cognitive fatigue of hunting for subtle, plausible hallucinations across fifty pages of contract terms proved more draining than drafting the memorandum from raw documents. Within fourteen months, the company's internal compute invoice from Microsoft Azure exceeded the entire baseline software licensing budget of the claims division, while overall policy turnaround times accelerated by a negligible eight percent.
When the contract reached its renewal anniversary last month, the insurer did not renew. They severed the integration, canceled the license, and reverted sixty percent of the workflow to deterministic SQL rules and senior human underwriters. This scenario is playing out across banking, healthcare administration, customer service, and commercial litigation.
The Impending Gross Margin Compression Crisis
What happens to an industry valued at hundreds of billions of dollars when its underlying revenue quality is exposed as non-recurring and its gross margins compress by thirty percentage points?
The public markets have historically valued pure software businesses at high-single-digit to double-digit revenue multiples precisely because incremental revenue falls directly to free cash flow. In contrast, IT consulting firms, system integrators, and outsourced service providers—the Accents, Infosyses, and Cognizants of the world—trade at modest valuations of one-and-a-half to three times revenue. They trade there because every dollar of new revenue requires hiring more human bodies to deliver it.
If enterprise AI vendors must maintain embedded teams of customer-success engineers, prompt architects, and deterministic harness builders to keep their models from breaking corporate infrastructure, they are not software companies. They are high-cost, specialized consulting firms masquerading as software platforms.
 Corporate Balance Sheet Markup
The arithmetic will not be denied. As enterprise buyers demand hard commitments on unit economics and refuse to sign uncapped token-passthrough contracts, AI vendors are forced to absorb the volatility of inference compute on their own balance sheets. Every time an underlying frontier model architecture scales up in parameter density to reduce reasoning errors, the vendor's serving cost jumps by an order of magnitude, while their contractual pricing remains pinned to fixed enterprise seats.
The Accounting Fiction of Capitalized Inference
To fully comprehend how enterprise software vendors have obscured this margin collapse from public scrutiny, one must examine the dark corridor where GAAP accounting rules intersect with cloud capacity commitments. Over the past three fiscal years, major venture-backed software entities signed binding multi-year take-or-pay infrastructure contracts with public cloud hyperscalers totaling tens of billions of dollars.
Under standard procurement agreements, if a vendor fails to consume their contracted minimum GPU hours, the shortfall is billed as an idle infrastructure penalty. Rather than recognizing these penalties as immediate operating losses, financial controllers have systematically capitalized portions of these commitments under long-term software assets, arguing to auditors that the compute was utilized to build proprietary fine-tuned model checkpoints.
In reality, ninety percent of those token cycles were burned running speculative customer proofs-of-concept that never converted into paid production renewals. When an enterprise pilot churns after twelve months, the vendor is left holding an unamortized capital asset on its balance sheet representing compute spent on a client that has already walked out the door. The moment auditors force a full impairment write-down of these synthetic software assets, the declared book value of dozens of unicorn AI platforms will evaporate overnight.
The Reckoning Behind the Balance Sheet
We are rapidly approaching the moment of financial exhaustion. The venture subsidy that floated the initial wave of synthetic enterprise tooling is dissipating as crossover investors pull back from late-stage funding rounds that fail to demonstrate net revenue expansion.
The companies that survive the coming shakeout will not be those that boast the most dazzling stochastic demonstrations on stage. Survival will belong to the austere, disciplined engineering organizations that treat compute as a precious, finite physical resource—teams that reject the lazy dogma of throwing trillion-parameter general models at narrow domain problems and instead build small, sovereign, deterministic pipelines that run on twenty-watt silicon.
For the rest of the enterprise landscape, the bill has arrived. The era of claiming two-million-dollar custom integration projects as high-margin ARR is over. When the auditors finish their work, Wall Street will look at the enterprise software market and discover that the emperor was not wearing software at all; he was wearing an army of contract engineers working overtime to hide the hallucinations of a very expensive machine.